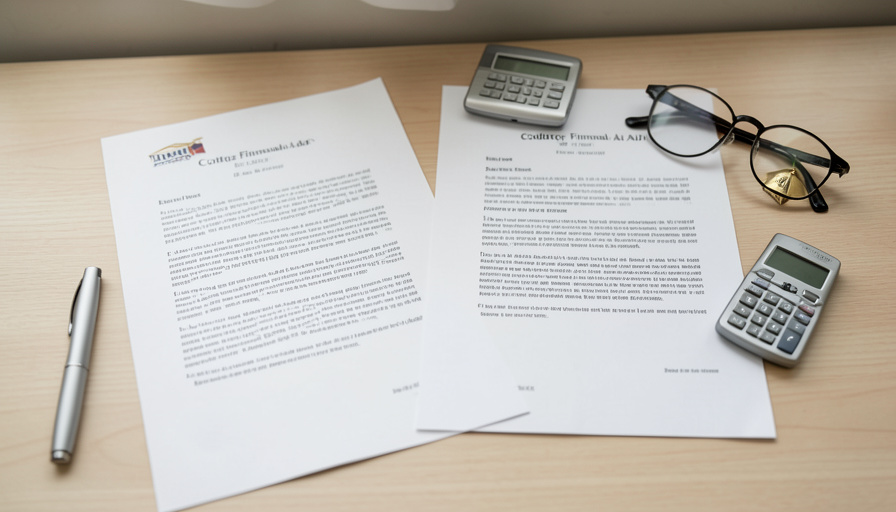

Two award letters can show the same bottom-line number and still cost your family thousands of dollars apart, which is exactly why the comparison is so easy to get wrong.
Spring brings a stack of financial aid offers, and families sit down expecting to line them up and pick the cheapest school. The problem is that colleges do not write these letters the same way. One folds loans into the “aid” total, another leaves out housing entirely, and a third quietly front-loads the grant to freshman year. The data below shows how common that is, and the specific cost gaps worth asking about before you send a deposit and lock yourself in.
Key Takeaways
- An estimated 91% of colleges either omit or understate the real net price in their aid offers, so headline numbers rarely compare cleanly.
- Only about a third of families say their offer even showed the full cost of attendance, and loans are often mixed into the aid total.
- Before you commit, ask five questions: is this full cost or direct charges, how much is grants versus loans, is work-study guaranteed, does the aid renew, and what is the net price after grants alone.
Table of Contents
The numbers behind award letter confusion
The confusion is not a personal failing, it is baked into how offers are written. A federal review found the scale of it. In the Government Accountability Office’s study of a nationally representative sample of 176 colleges, an estimated 41% of schools did not include a net price at all and another 50% understated it, which together means about 91% of offers omit or lowball what a student would actually pay, according to the GAO report on financial aid offers. The same review measured offers against 10 best practices, and no college in the sample followed all 10, while roughly two-thirds followed half or fewer.
That is the core reason two letters resist a fair comparison. When one school subtracts loans to make its “net” look small and another leaves loans out but omits housing, the two totals are measuring different things. You are not comparing prices, you are comparing formatting.
Why two offers with the same total are not equal

Net price is the honest figure: the total cost of attendance minus only the money you never repay, meaning grants and scholarships. Loans and work-study do not reduce the price, they just change how you cover it. Yet many families never see a clean version of that math. In Sallie Mae’s research on aid offers, only 36% of families said their offer included the full cost of attendance, and just 27% said the letter clearly spelled out expected out-of-pocket costs, per the company’s 2026 findings on financial aid offer letters.
So a $28,000 “package” at one school and a $28,000 “package” at another can hide a wide gap. If the first is $24,000 in grants and $4,000 in loans, and the second is $8,000 in grants and $20,000 in loans, the sticker looks identical while the debt you carry is five times larger. The headline number is the least useful line on the page.
The hidden cost gaps to ask about
Before any deposit, run each offer through the same five questions. These are the gaps that families on forums like r/financialaid and r/ApplyingToCollege say caught them off guard after they had already committed:
- Is this the full cost of attendance, or only direct charges? Some letters list only tuition and fees and leave out housing, meals, books, and travel. Ask for the full cost of attendance so nothing is missing from the denominator.
- How much of this is grants versus loans? Separate the free money from the borrowed money yourself. Anything labeled a loan is a future bill, not aid that lowers the price.
- Is the work-study a guarantee, or just eligibility? A work-study line is permission to hold an eligible job, not a check that arrives automatically. You have to find the position and work the hours, and students often ask whether it is even guaranteed once offered.
- Does this aid renew for four years? Some grants are front-loaded to freshman year and shrink after that. Families are regularly blindsided when aid drops between freshman and sophomore year, so ask what renewal depends on.
- What is my net price after subtracting only grants and scholarships? Make each school give you that one number the same way. It is the only figure that lets you compare offers side by side.
Writing those five answers in a simple grid, one column per school, turns three mismatched letters into one clean comparison. If you already track spending, the same habit that powers manual cash budgeting works here: the number only means something once every school is measured the same way.
What families still get wrong about loans

Loans are where the biggest misreads happen, partly because they sit right next to grants and look like part of the award. In the same Sallie Mae research, one in five families (20%) did not realize loans could be included in the aid package at all, and 19% believed that any loan offered had to be accepted. Neither is true. You can decline or reduce a loan and still keep the grants, and doing so is often the smartest line-by-line edit you can make to an offer.
The comparison mindset that protects you here is the same one that protects a contractor deposit or any other large commitment, where the numbers and the questions matter more than the pitch. Our look at deposit dispute statistics covers that same instinct: know what you are agreeing to before the money moves.
This article is general information, not financial advice. Financial aid rules, costs, and offer formats vary by school and by year, and your situation may differ. For decisions about loans, grants, or a specific offer, confirm details with the college’s financial aid office and a qualified advisor.
Frequently Asked Questions
How do I compare two college financial aid offers fairly?
Reduce every offer to its net price, which is the full cost of attendance minus grants and scholarships only, never loans or work-study. Put each school in its own column and fill in the same lines: full cost, grants, loans, and the resulting net price. The federal Consumer Financial Protection Bureau also offers a tool to compare aid offers and costs. Only once the letters are measured the same way does the cheaper school become clear.
Why do financial aid offers understate the real cost?
Because there is no required format, and many schools subtract loans or leave out living costs, which makes the price look smaller. A GAO review found about 91% of colleges omit or understate the net price, and no college in its sample followed all 10 recommended best practices. The result is offers that read as cheaper than they are, so the burden of an honest calculation falls on you.
Do loans count as financial aid in an award letter?
They appear in the package, but they are borrowed money you repay with interest, not aid that lowers the price. One in five families do not realize loans can be bundled into the offer, and many think an offered loan must be accepted. It does not. You can decline or reduce a loan while keeping every grant and scholarship in the letter.
Is work-study guaranteed if it is on my offer?
No. A work-study line means you are eligible to hold a qualifying job and earn up to that amount, not that the money arrives on its own. You still have to find and work the position, and earnings come as a paycheck over the term. Treat it as potential income you have to earn, not a discount on tuition.
Can financial aid change after freshman year?
Yes. Some grants and scholarships are front-loaded to the first year and shrink afterward, and aid can also change if your family finances or enrollment shift. Ask each school whether the aid in the letter renews for all four years and what conditions apply, so a strong freshman offer does not turn into a much larger bill as a sophomore.
The Bottom Line
An award letter is a sales document as much as a statement of aid, and the numbers are arranged to look their best. The fix is not complicated: strip each offer down to net price after grants alone, separate loans from free money, and ask whether work-study and grants are guaranteed year after year. Do that across every school on the same grid, and the letters that were designed to resist comparison finally line up. For more guidance on paying for school, browse Wayodd’s Education section.






No Comments
Leave a comment Cancel